Your Customers Are Not Always Your Users. Does Your Proposal Know?
Who pays for your innovation, and who actually uses it? The Coca-Cola example reveals a distinction that can change your market sizing, validation strategy and EU funding proposal.
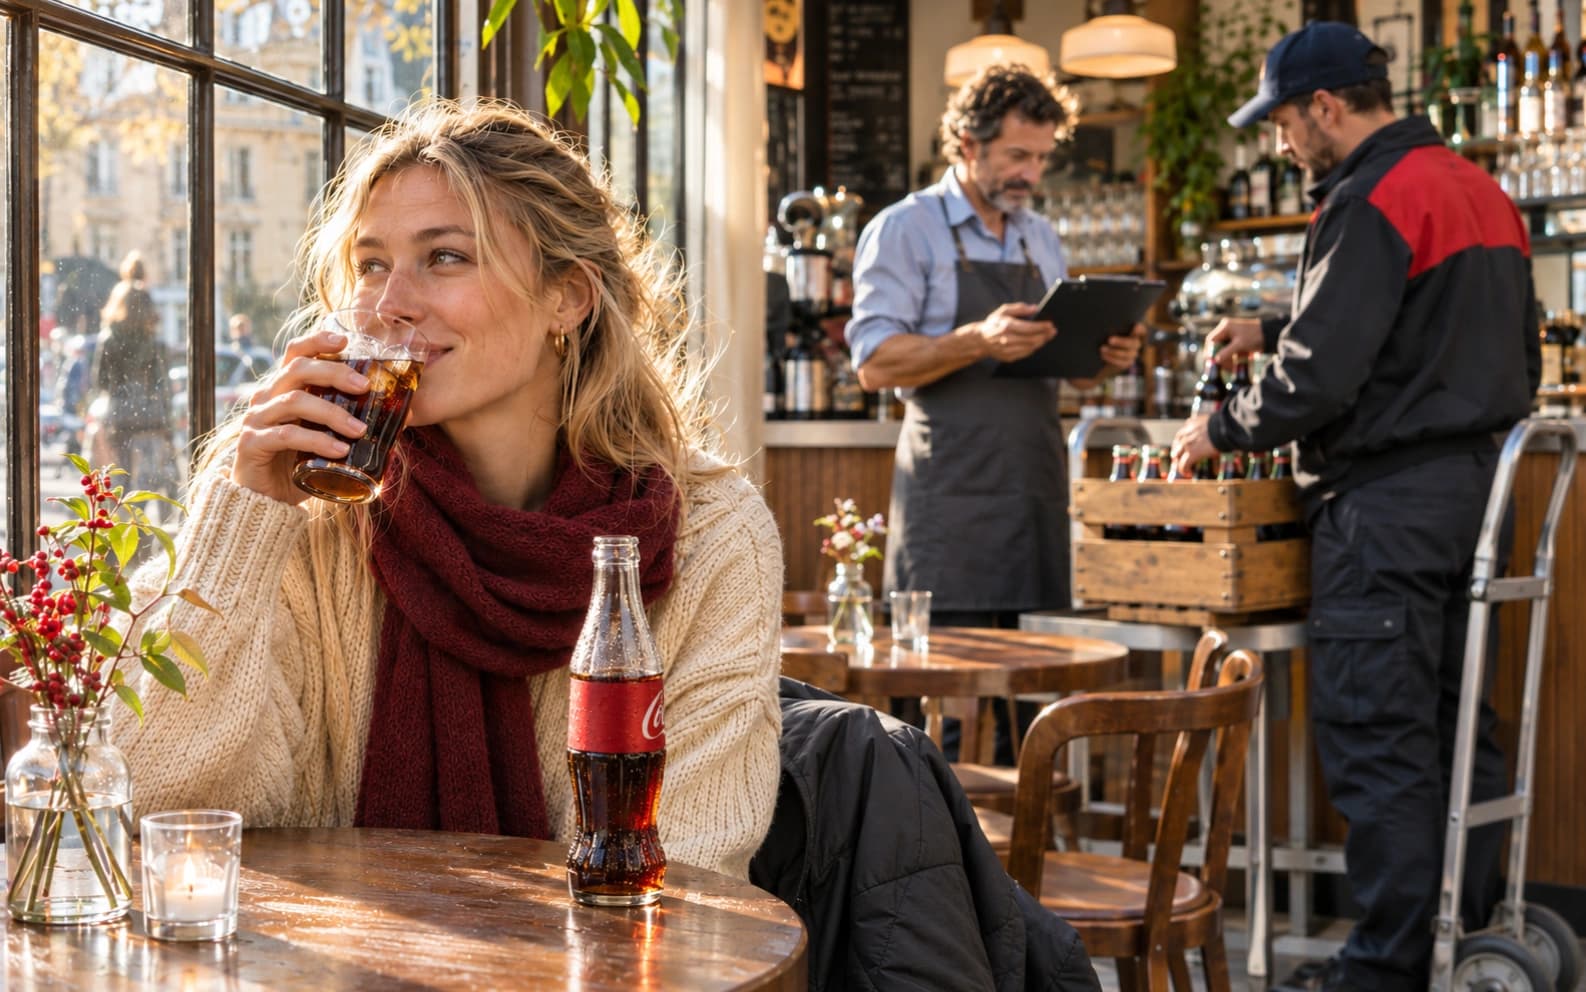
You drink Coca-Cola. But are you the customer Coca-Cola sells to?
You walk into a café, order a Coca-Cola and drink it. Of course you are a customer of the café. But are you also the direct commercial customer of the company making and distributing the drink? Not necessarily. This small distinction reveals a surprisingly important question for companies preparing an EU funding proposal: are you describing the organisations that will buy your innovation, or the people who will use it?
The Coca-Cola business system offers a familiar example. The Coca-Cola Company typically sells concentrates and syrups to bottling partners. Bottlers and other beverage operations supply retailers, restaurants and hospitality establishments. These outlets sell beverages that people ultimately consume. Depending on the country and channel, the supply chain may take different forms, including direct-to-consumer sales. The important point is that a brand can serve an enormous consumer audience without each consumer being its direct commercial customer.
This is not an invented distinction. The 2025 Form 10-K of The Coca-Cola Company explains both its concentrate business, which typically sells to bottling operations, and its finished-product business, which sells to retailers, distributors and wholesalers. It also describes the importance of connecting with consumers. The commercial relationship and the consumption relationship are interconnected, but not identical.
And here is the interesting part: advertising often speaks directly to people drinking the beverage, rather than to the procurement teams at supermarkets or cafés. Why? Because end-user demand can influence the buying decisions of the commercial customer. If consumers ask for a drink, the businesses selling beverages have a reason to stock it. That does not eliminate retailer margins, distribution terms or shelf-space decisions; it shows why both sides matter.
For an innovator applying to the EIC Accelerator, Eurostars or another EU funding programme, getting this distinction wrong can undermine the market narrative long before an evaluator reaches the revenue forecast.
Customer vs end-user: two questions, not two buzzwords
In a commercialisation analysis, the customer is the person or organisation purchasing or contracting the product or service under the business model being assessed. The end-user is the person or organisation that ultimately uses the technology, product or service. In consumer-goods markets, an end-user is often called a consumer. For the purposes of this article, *consumer* is simply the natural term for the person who drinks the Coca-Cola; it is not a third market segment that must automatically be quantified.
Nor must a company always have separate customer and end-user segments. A consultant who buys and uses a specialist software subscription may be both. A small business buying a tool for its own operations may play both roles. Segmentation should reflect the real business model, not an artificial attempt to populate two boxes in a proposal.
The more difficult situations arise when the economic buyer, procurement decision-maker, payer and practical user differ. They sometimes belong to the same organisation, but have different objectives. The resulting adoption problem is not solved simply by saying the technology is innovative.
The Coca-Cola lesson: demand and purchasing power are different
Imagine a supermarket evaluating whether to carry a beverage. The retailer considers expected turnover, gross margin, delivery reliability, shelf capacity, price and competing products. The person drinking it may care about taste, brand preference, availability and price at the point of sale. Both groups shape the outcome, but through distinct decisions.
A brand campaign can encourage consumers to request a particular drink. That increases the appeal of stocking it. Yet consumer awareness alone does not guarantee that the retailer will accept supply conditions. Conversely, extensive distribution does not ensure that the product will sell if consumers do not want it.
For innovation projects, the analogous problem is everywhere. Users can enthusiastically endorse a technology while procurement departments reject its cost or integration burden. Buyers can approve a product on paper while users abandon it because it interrupts daily workflows. Validating desirability with users is not the same as validating a purchasing decision with customers.
This matters for evaluators because the evidence behind the market section must support the claim being made. A proposal reporting 50 positive user interviews should not casually describe them as 50 potential purchasing organisations. Likewise, five supplier meetings cannot establish that 5,000 end-users will adopt the solution.
Healthcare: hospitals buy, clinicians use
Consider a startup developing an advanced surgical navigation platform. Under an institutional sales model, the hospital or healthcare provider is the customer. Surgeons and clinical teams are end-users. Patients may be the ultimate beneficiaries of improved outcomes, but they are not automatically customers or direct users of the system.
The hospital may ask about acquisition price, maintenance, data security, reimbursement, procurement rules, staff training and compatibility with existing equipment. A surgeon may focus on clinical performance, precision, ease of use, procedure time and reliability. Those requirements overlap, but they are not interchangeable. A promising pilot with surgeons does not by itself demonstrate that a hospital has approved a budget.
This distinction affects the evidence strategy. Clinical usability studies and workflow observations can support user acceptance. Procurement interviews, budget-holder discussions, contract negotiations and purchase commitments can support commercial demand. Clinical outcome data may demonstrate benefits for patients. All are useful, but each answers a different question.
The same distinction changes market sizing. If the revenue model is a subscription per hospital, the commercial denominator is eligible purchasing hospitals or equivalent procurement units, not the number of surgeons or patients. Patient volumes may help estimate usage intensity and impact; they cannot simply be multiplied by the hospital subscription price.
Education: institutions buy, teachers and students use
Imagine an AI-assisted learning platform licensed annually to schools or universities. A purchasing institution may be the customer, while teachers and students represent different end-user groups. A public education authority could be the actual contracting party in some markets. The precise arrangement must be checked rather than assumed.
The buyer may prioritise cost, accessibility, privacy, system integration and procurement compliance. Teachers may want useful feedback, time savings and curriculum alignment. Students may care about ease of use and learning effectiveness. A platform can appeal to students but still face institutional barriers to purchase.
Suppose a company has 20 contracts with schools serving 15,000 students. It would be misleading to state that it has 15,000 customers if the schools sign and pay for the contracts. The startup may have 20 paying organisational customers and a much larger number of end-users. If pricing is based on active student seats, the number of seats matters to revenue, but it still does not make every student a separately acquired customer.
Here too, the commercial logic must match the metric. Adoption rate among teachers, active student usage, renewal rate among schools and contract value measure different things. Combining them without explanation creates an apparently impressive but analytically weak proposal.
Industry: manufacturers buy, operators use
Now consider an inspection system for industrial production lines. The manufacturer operating the factory may purchase the system. Quality-control technicians and production operators may use it daily. Management may expect reduced scrap, higher throughput or lower downtime; operators may prioritise alert accuracy, simplicity, reliability and safe workflow integration.
A technical demonstration can show that the inspection model works. A trial with operators can show that it is usable. A discussion with the plant purchasing manager can test procurement conditions. A financial model can estimate savings, assuming its inputs are validated. None of these pieces of evidence automatically substitutes for the others.
When customer and end-user are the same
The distinction is not an invitation to invent unnecessary complexity. For a professional purchasing a software subscription for personal use, customer and end-user are often identical. The same can be true for a person purchasing a wearable for their own monitoring or an entrepreneur subscribing to a digital tool.
What matters is not that every proposal must contain two separate population estimates. What matters is that the proposal never silently switches from one population to another to support a larger revenue or impact claim.
Market sizing: one wrong denominator can invalidate the result
Market numbers become misleading when applicants confuse purchasing entities with the people or cases served. Consider an entirely hypothetical AI diagnostic platform sold to hospitals on an annual institutional subscription.
Assume, for illustration only, that a defined geographical segment contains 600 potentially eligible hospitals, 12,000 clinicians who could use the software and 1.2 million patient cases that could benefit. Suppose the annual licence price is €25,000 per hospital. Under a simplified one-licence-per-hospital model, 600 multiplied by €25,000 gives a theoretical €15 million annual opportunity at full penetration, before exclusions, adoption barriers, discounts, procurement constraints or implementation capacity.
Multiplying the 12,000 clinicians by €25,000 would not produce a valid market estimate under that pricing model. Multiplying 1.2 million patient cases by €25,000 would be even less defensible. Clinicians inform user adoption; patient cases inform possible utilisation and impact; hospitals determine the purchasing base in this example. The denominator must match the revenue unit.
If the software were instead priced per clinician seat or per test, the relevant calculation would change. That is why the revenue model must be fixed before presenting the market size. Applicants should also separate total market opportunity from the serviceable segment and the realistically obtainable share, supported by adoption assumptions and delivery capacity.
This is closely related to our article Does your project have a higher market share than Tesla?, which explains why market-share figures need a bottom-up rationale rather than an arbitrary percentage.
User interviews are not purchase commitments
Suppose a startup reports that 40 clinicians tested its prototype and 90% said they would like to use it. The finding could support an argument about perceived usefulness, provided the sample, questions and study design are appropriate. It does not automatically establish that hospitals will buy the product.
Perhaps the clinicians lack purchasing authority. Perhaps their employers have incompatible IT systems or strict procurement requirements. Perhaps the proposed price does not fit an approved budget. The user feedback may still be valuable, but describing it as confirmed paying demand would overstate the evidence.
The reverse can also happen. A hospital procurement team may be interested in expected savings, while clinicians raise workflow or safety objections. A strong validation plan therefore addresses both sides with suitable methods. Customers may be interviewed about purchasing criteria, budget, payment model, contract duration and competitive alternatives. End-users may be observed or surveyed about unmet needs, performance, usability, integration and practical adoption barriers.
For related guidance on turning broad claims into evidence that can be assessed, see What cannot be measured does not exist. A proposal should specify the tested claim, the metric, the source, the limitations and the conclusion that the result actually supports.
Segment both groups, but only where the distinction matters
Customer segmentation should follow the commercial model. Relevant criteria may include sector, size, country, procurement arrangements, budget capacity, digital maturity, installed infrastructure and regulatory requirements. For a hospital sale, customer segments might distinguish institutions by applicable procurement model or technology compatibility, where evidence shows that those differences affect purchasing feasibility.
End-user segmentation should reflect actual usage needs. The relevant variables could be professional role, workflow, technical experience, frequency of use, clinical specialty, production environment or the severity of the problem addressed. For example, a platform designed for specialised radiology teams should not assume every healthcare professional is a potential active user.
A useful segmentation is not necessarily complicated. It starts with a focused beachhead market: the buyers most likely to purchase and the users most likely to obtain measurable value. Then it demonstrates how customer demand, user acceptance and route to market fit together. This provides a much stronger basis for a commercialisation plan than presenting the entire European population as a homogeneous opportunity.
Crucially, estimates must remain consistent across sections. If market size is presented in hospitals, revenue projections should explain hospital contracts and pricing. If impact is expressed in patient cases, the proposal should show the link between deployed licences, clinician usage and cases served. If early traction is expressed in pilot sites, the text must not silently call those pilots paying customers.
The broader narrative starts with a real need. Our article No problem, no grant explains why a well-defined problem is the foundation of a credible innovation and market argument. Differentiating buyers from end-users is one way to make that problem definition more commercially useful.
Does this distinction matter for every EU funding programme?
Its significance depends on the funding instrument and project maturity. For commercially oriented applications, including many EIC Accelerator and Eurostars projects, a credible business case needs to explain who buys, who uses, what each group values and why adoption can realistically turn into revenue. The depth of the evidence should be appropriate to the maturity of the innovation and the applicable call requirements.
For collaborative Horizon Europe projects, end-users may play a major role in needs analysis, co-design, demonstration, uptake and expected impact even where immediate product sales are not central. For research-focused actions, inventing a near-term customer acquisition plan may be inappropriate. The correct framing follows the call, work programme, evaluation criteria and project objectives, not a universal sales template.
In all cases, an applicant should avoid treating customer and end-user segmentation as an official requirement unless the relevant call documentation actually makes it one. The distinction is an analytical discipline that can improve the credibility of commercialisation, adoption and impact arguments when these matter to the proposal.
Five questions to test your proposal
Before submitting, ask five questions and check that the answers are consistent with the rest of the application:
- Who pays or contracts? Name the purchasing entity, economic buyer, procurement process and channel relevant to the revenue model.
- Who uses the innovation? Define the actual users, their unmet needs and the outcomes the solution is designed to improve.
- Where do the groups overlap? State whether customer and end-user are the same in each segment; do not invent a distinction where none exists.
- Which number belongs in which calculation? Separate customers, contracts, licences, seats, sites, users, transactions and beneficiaries. Tie each to a clear metric.
- What does the evidence prove? Distinguish user acceptance, willingness to pay, budget availability, procurement commitment, technical performance and realised impact.
A proposal that answers these questions can make more defensible choices about targeting, revenue forecasts, go-to-market activities, pilot design and impact measurement. One that cannot may have an important weakness in its commercial logic, even if the technical innovation is excellent.
Know who buys. Know who uses. Show how the two connect.
The next time you see a Coca-Cola advertisement, notice who it addresses. The person enjoying the drink may not be the direct commercial customer of the beverage company, but consumer preference can influence decisions throughout the distribution chain. This is the lesson that makes the example relevant far beyond soft drinks.
Some innovations have one group of people who both buy and use them. Others involve purchasing organisations, operational users and beneficiaries with very different priorities. Neither configuration is automatically better. What matters is that the applicant understands the relationships, quantifies the correct populations and validates the assumptions that connect technology adoption with commercial demand.
Knowing who benefits from your innovation is not necessarily the same as knowing who will pay for it. A credible EU funding proposal needs to understand both. Before submission, Ruthless Evaluator can help critically review the evidence, internal consistency and market narrative of a proposal against the selected programme requirements.
Run an evaluator grade review on the draft
Upload a version, select programme context, and get structured feedback you can act on.